Nvidia stock valuation debated across financial outlets on October 19
 4 sources · شبكة تواصل الإخبارية · The Motley Fool · Yahoo Finance
- Boom: Motley Fool cited Nvidia trading at 8 times projected 2030 earnings as a valuation benchmark
- Neutral: Nvidia's stock price has lagged behind its earnings growth, per Yahoo Finance analysis
- Boom: Seeking Alpha identified a recent price dip as a potential entry point based on valuation
The story in full
Multiple financial outlets published analyses of Nvidia's stock valuation on October 19, 2026, examining whether the current share price represents a buying opportunity relative to the company's earnings growth. The Motley Fool framed its coverage around a forward price-to-earnings ratio of 8 times projected 2030 earnings, while other outlets noted that the stock price has lagged behind earnings growth.
Analysis
351 wordsOn October 19, 2026, several financial outlets published analyses focused on whether Nvidia's stock price represents fair value relative to the company's earnings trajectory. The Motley Fool examined the claim that Nvidia is trading at roughly 8 times projected 2030 earnings, framing that ratio as a potential indicator of undervaluation. Yahoo Finance published two separate pieces the same afternoon, one arguing that the stock price has lagged behind what the outlet described as massive earnings growth, and another asking more broadly whether the stock is priced correctly. Seeking Alpha identified a recent dip in Nvidia's share price as an appealing entry point based on its own valuation framework.
The debate matters because Nvidia sits at the center of the infrastructure buildout powering current AI development, and its stock price is widely treated as a proxy for investor confidence in that buildout continuing. A forward price-to-earnings ratio measured against 2030 projections carries significant uncertainty, since those projections depend on assumptions about AI hardware demand, competition from AMD and custom chip efforts at major cloud providers, and the pace of model training scaling. Whether the stock's lag behind earnings growth reflects a buying opportunity or a market signaling caution about those assumptions is genuinely contested.
None of the Pro-AI, Anti-AI, or Middle Ground camps have posted reactions to this specific story yet. In a situation like this, the Pro-AI camp would typically argue that Nvidia's dominant position in AI accelerator hardware justifies confidence in long-range earnings projections, making a low forward multiple a clear opportunity. The Anti-AI camp would more likely treat bullish valuation arguments as evidence of continued hype disconnected from sustainable fundamentals. A Middle Ground position would generally emphasize that 2030 earnings estimates are speculative enough to warrant caution regardless of how attractive the multiple appears on paper.
The argument is unlikely to resolve without Nvidia's next earnings report, which would either reinforce or complicate the earnings growth narrative that underlies all three outlets' analyses. Any update to guidance on data center revenue, which has been the primary driver of recent earnings expansion, would be the most direct signal to watch.
Where do you stand?
Add your take
0 reader votesSign in with Google to pick a side and post. Your vote moves the story's Doom / Boom score.
Sources
5 articles from 4 outlets- شبكة تواصل الإخباريةIs Nvidia Stock Really Trading for Just 8 Times 2030 Earnings?
- The Motley FoolIs Nvidia Stock Really Trading for Just 8 Times 2030 Earnings?
- Yahoo FinanceIs Nvidia (NVDA) Stock Priced Right?
- Yahoo FinanceNvidia (NVDA) Stock Price Lags Massive Earnings Growth—A Compelling Value Opportunity
- Seeking AlphaNvidia: The Recent Dip In Price Makes An Appealing Entry Point Per My Valuation (NVDA)
Related Splits
All stories →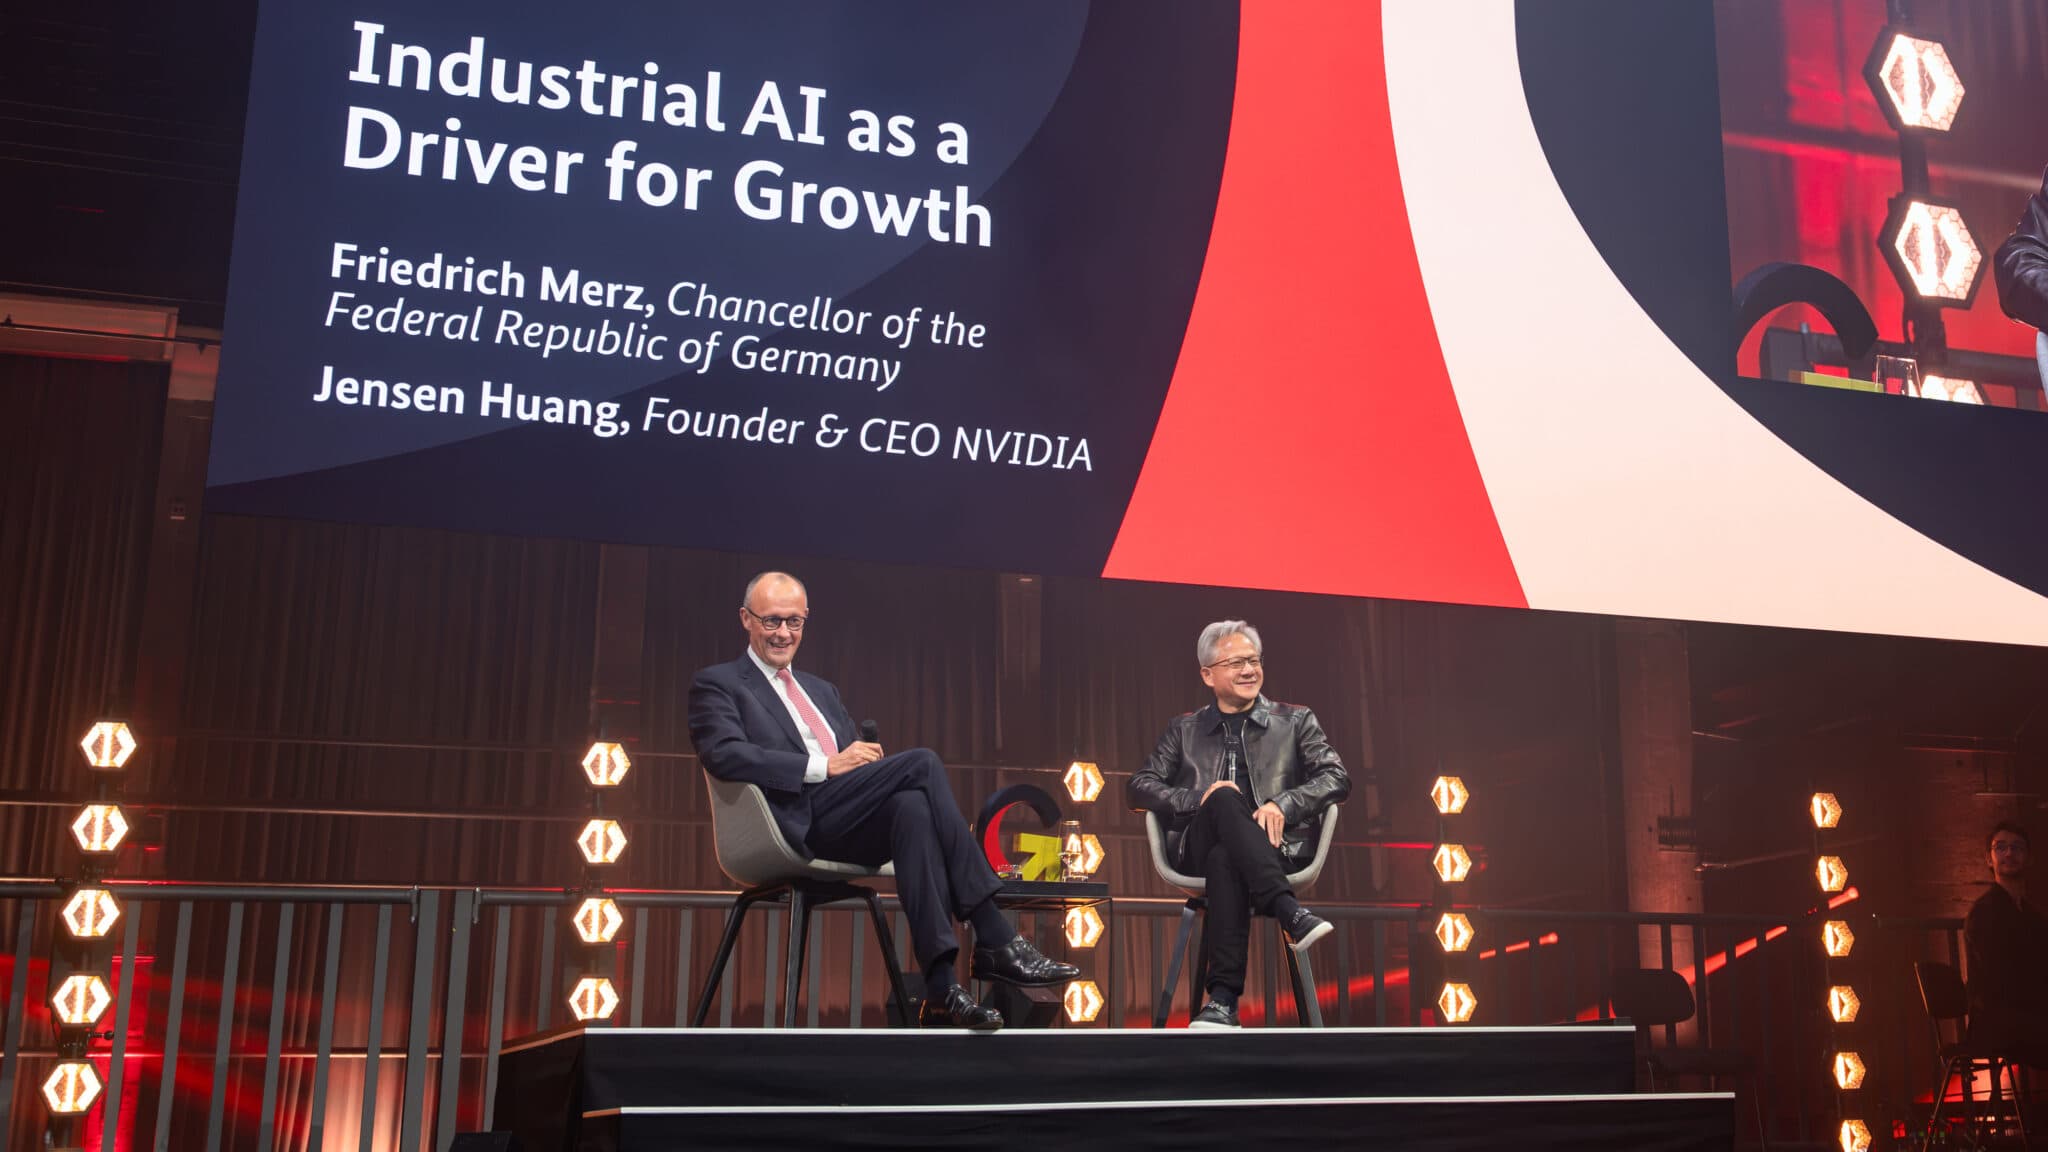
Jensen Huang and Friedrich Merz meet in Berlin on industrial AI
On October 19, 2026, NVIDIA CEO Jensen Huang and German Chancellor Friedrich Merz held a public conversation at Kraftwerk, a former power station in Berlin, to...
Amazon launches TorchNeuron to run PyTorch models on Trainium chips
Amazon announced TorchNeuron on October 19, 2026, a software tool that lets developers run PyTorch-based AI models on AWS Trainium chips without rewriting their code. The...
NVIDIA runs 104-qubit fault-tolerant quantum simulation at Jülich
On October 19, 2026, NVIDIA ran a record-scale simulation of fault-tolerant quantum computing using the JUPITER exascale supercomputer at the Jülich Supercomputing Centre in Germany. The...